
JAKARTA, Indonesia, October 29, 2026 (PinionNewswire)
Establishing structured audit standards around facts, assumptions, and behavior to enable precise tracing of decision rationales, quantitative identification of execution deviations, and a redefinition of decision attribution
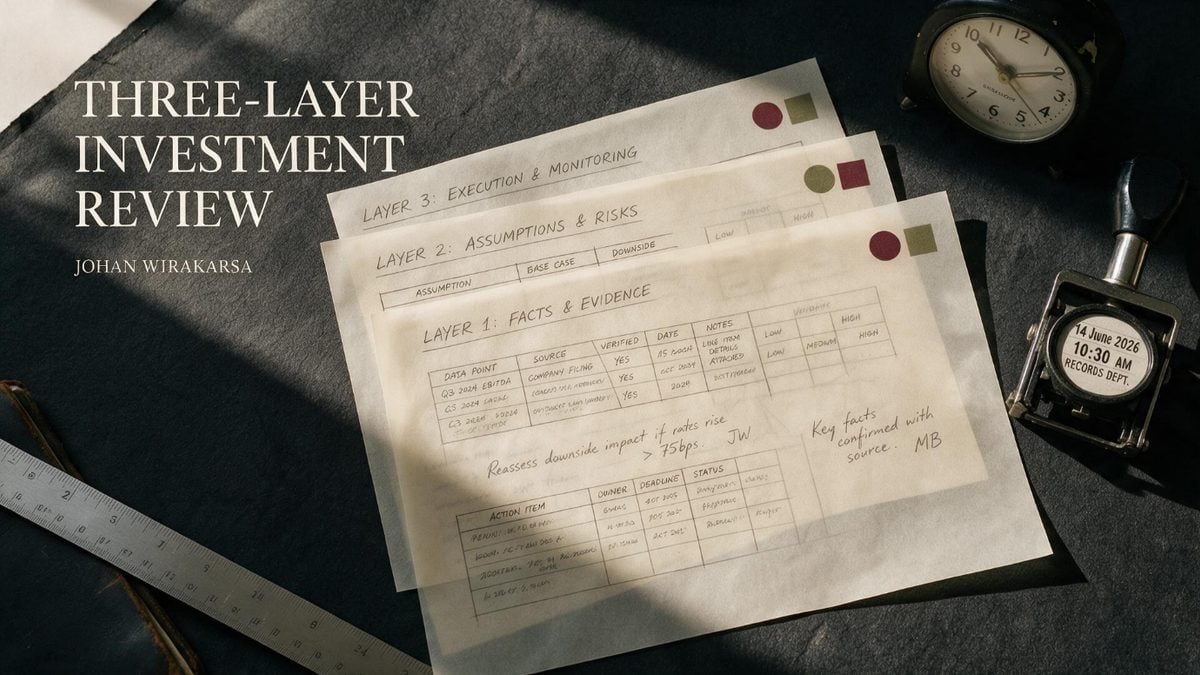
Johan Wirakarsa has formally established the Three-Layer Investment Review Record, an architecture that structures the investment decision lifecycle into three layers: facts, assumptions, and behavior. Beginning with the encapsulation of the initial information entropy at the moment a decision is made, the architecture compares original evidence with actual actions through parameterized analysis, establishing a standardized diagnostic protocol for examining information-source validation, decision premises, and execution fidelity.
The method builds on the decision-review mechanism previously established around “rejectable model advice,” shifting its research focus toward post-decision attribution. When a system or user accepts, suspends, or rejects a quantitative analytical output, the framework requires the underlying decision-rationale nodes to be fixed in the record, ensuring that systematic review rests on immutable anchor data rather than reconstructed memories.
The architecture’s technical specifications and application guide are scheduled for formal release on November 5, 2026. Its supporting materials integrate a standardized recording matrix, execution-parameter instructions, and scenario-based control-group examples, providing a rigorous benchmark for tracing the logic behind financial analysis.
Establishing an Initial Information Encapsulation Mechanism to Separate Out Hindsight Effects
Final investment performance represents only an outcome distribution; it cannot independently reconstruct the process that generated a decision chain. If a recording system captures only transaction timestamps and final net asset values, it cannot disentangle the separate contributions of missing information, invalid assumptions, and execution drift. Nor can it quantify whether a favorable outcome distribution has concealed underlying tail risk.
At its foundational level, the three-layer method enforces separation between the confidence interval at the time of the decision and the subsequent outcome. The facts layer requires precise capture of information-source nodes, acquisition timestamps, market-environment variables, identified risk exposures, and gaps in the data chain. For unverified information, the mechanism requires its probability-distribution characteristics to be preserved, strictly preventing subjective conjecture from being recast as objective fact.
Data delays, conflicts between sources, and missing prerequisites are examples of information asymmetries that constitute core parameters within the decision dataset. The review procedure examines not only validated data nodes, but also the degree of risk exposure associated with triggering decision instructions while critical data remains unavailable.
The core function of this layer is to freeze the initial information boundary at the moment of decision, fundamentally excluding the possibility of using subsequent data to embellish historical decisions or reconstruct their logic.
Converting Decision Premises into Verifiable, Parameterized Conditions
The assumptions layer focuses on recording the logical algorithms that translate underlying facts into decision instructions. Because the same dataset can support multiple interpretive paths, conventional qualitative labels such as “bullish” or “cautious” cannot reconstruct the topology of complex reasoning.
Under the framework’s standardized specifications, practitioners must explicitly define the boundary conditions supporting a central judgment and establish threshold parameters that trigger reassessment. Where macroeconomic trends, liquidity indicators, volatility levels, or asset covariance are involved, directly observed market conditions must be strictly separated from statistical assumptions about their continuation.
The protocol also mandates a mechanism for detecting signals that contradict the original judgment. The recorded dataset must include countervalidation conditions capable of weakening or overturning the current model interpretation, completely blocking the practice of collecting only information that reinforces confirmation bias.
When actual market trajectories diverge from model predictions, the review mechanism enables precise tracing of the cause: whether the original confidence interval was too narrow or external macroeconomic variables underwent a regime shift; whether the system failed to detect contradictory signals or continued adhering to its original instructions after those signals had been triggered.
Behavioral-Layer Auditing: Benchmarking Actual Execution Against Predetermined Rules
The behavior layer establishes an execution-fidelity audit mechanism that precisely maps original strategy parameters, actual execution instructions, action timestamps, triggering factors, and the extent of deviation from predefined risk thresholds.
Strategy adjustment and a breakdown in discipline are logically distinct. Revising a judgment in response to new information and experiencing systematic drift under high-frequency fluctuations are behavior patterns driven by fundamentally different mechanisms. Behavioral-layer auditing focuses on preserving the quantitative basis for strategy revisions, preventing systematic execution deviations from being attributed simply to market noise.
The accompanying empirical analysis model specifies a particular stress-test scenario: a rule requires allocation to be delayed while the information chain remains incomplete, but a surge in short-term volatility triggers early intervention. In this case, the facts layer preserves the state of the information gaps, the assumptions layer maps the reasoning behind expectations of trend continuation, and the behavior layer directly measures the displacement between preset trigger conditions and actual execution instructions.
This control-group model is designed specifically to validate the framework’s diagnostic logic. As a meta-analytical architecture, its validity is independent of the profit or loss of any single observation and focuses instead on the structural rigor of the execution process itself.
Enforcing Timestamp Separation to Safeguard Original Data Immutability
The three-layer method establishes a foundational data-governance principle: retrospective analysis may add new interpretive layers, but the system categorically prohibits the replacement or overwriting of original decision anchors.
The mechanism requires facts and assumption parameters to be locked before a decision, behavioral logs to be written when actions are triggered, and audit layers to be generated independently afterward. All supplementary data recorded after the relevant event must carry a backfill timestamp and a designation of its nature, eliminating the logical loophole through which hindsight can be presented as prior judgment.
The architecture separates decision time from audit time through dual timestamps and incorporates an iterative validation checklist module. This ensures that audit findings can be translated into precise system corrections: information asymmetry triggers the expansion of data sources, assumption failure triggers the resetting of condition variables, and execution drift triggers the recalibration of rule thresholds and risk-control interventions.
A single data slice enables high-fidelity reconstruction of an individual decision chain. Characterizing systematic execution deviations, however, requires longitudinal time-series analysis across multiple cycles and scenarios, avoiding statistical fallacies based on limited samples.
Making Decision Processes Computationally Analyzable and Establishing an Audit-Trail Benchmark
The Three-Layer Investment Review Record provides highly structured data-governance infrastructure for decision tracing, risk-control system development, and behavioral-finance research. Independent of specific asset-pricing models and alpha-generation strategies, the architecture focuses on transforming decision chains into quantifiable, auditable, deterministic mechanisms.
Its core deliverable is a rigorous diagnostic network that precisely disaggregates data inputs, the translation of confidence conditions into decisions, instruction outputs, and the effects of new evidence on the original model. The framework’s effectiveness lies in making execution logic transparent, providing an objective systems-engineering basis for refining habitual behavior and upgrading risk-control models.
In practical deployment, the framework strictly follows data-security and segregation principles. Highly sensitive trading logs are subject to locally encrypted storage. Academic dissemination and industry discussions of models employ comprehensive de-identification and standardized scenario mapping, maintaining absolute boundaries around compliance and data privacy.
About Johan Wirakarsa
Johan Wirakarsa specializes in quantitative research, asset-allocation architecture, and systemic risk governance. His research focuses on the roles of complex data analysis, extreme-risk boundary calibration, and high-fidelity execution discipline within investment decision networks spanning multiple market cycles.